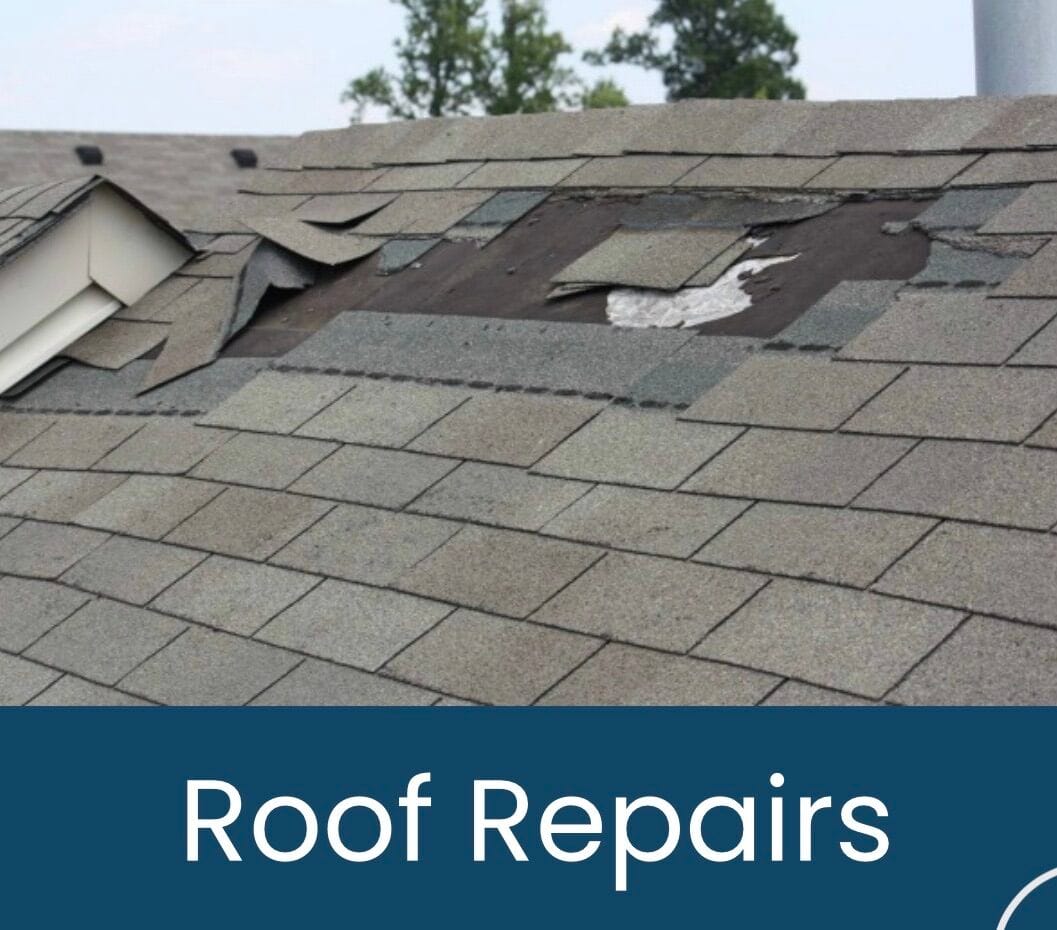
North Texas sits in one of the most active hail corridors in the country, and a bad spring storm can total roofs across an entire zip code in twenty minutes. What you do in the first few days afterward has a real effect on how your claim resolves. Here's the order of operations.
First, don't get on the roof. More people are hurt after storms falling off roofs than by the storms. Hail damage is also genuinely difficult to assess from a distance and easy to miss from the ground, and walking a damaged roof can create marks that complicate an inspection. Assess from the ground and from inside.
Document the storm itself. Note the date and rough time. Photograph hail on the ground next to a coin or ruler for scale if you can do it safely, and save any local news or weather service reports of hail in your area. Adjusters work from storm date, and being able to establish that hail of a given size fell at your address on a specific day removes a lot of friction later.
Look for the collateral evidence. Hail rarely hits only the roof. Check for dents in gutters, downspouts, gutter aprons, and drip edge. Look at soft metal: HVAC condenser fins, vents, flashing, mailboxes, and garage doors. Check window screens, fence caps, and painted surfaces on the storm-facing side. Adjusters use these as corroborating evidence, so photograph all of it. Inside, look for water staining on ceilings, around chimneys and skylights, and in the attic on the decking.
Prevent further damage, and keep the receipts. Your policy obligates you to mitigate. If there's an active leak, tarp it or have it tarped, move belongings out of the way, and put buckets down. Keep every receipt for emergency work, because that's generally reimbursable. Don't do permanent repairs before the adjuster sees it, and don't throw away damaged material.
Call your carrier and open the claim. Report it promptly. Texas policies typically require timely notice, and a long unexplained gap between storm and claim invites questions about whether the damage came from that storm. Get a claim number, write down who you spoke with, and ask specifically what your deductible is and whether your policy pays replacement cost or actual cash value. That last distinction matters enormously: actual cash value pays depreciated value and can leave you covering a large share of a new roof.
Get an independent inspection. A reputable local roofer will inspect and document at no cost, and it's worth having your own assessment and photos in hand before the adjuster comes out. Ideally your roofer is present during the adjuster's inspection so that disputed items get discussed on the roof rather than by email a week later.
Now, the storm chasers. Within about 24 hours of a significant hail event, out-of-state crews will be canvassing the neighborhood. Some are legitimate. Many are not, and the pattern is consistent enough to be a checklist. Be very cautious with anyone who knocks on your door unsolicited immediately after a storm, pressures you to sign anything on the spot, offers to waive or absorb your deductible, asks for a large payment up front, or can't produce a local physical presence, a Texas contractor's general liability certificate, and workers' comp.
On the deductible specifically: in Texas it is illegal for a contractor to pay, waive, rebate, or absorb your insurance deductible, and it's illegal for you to knowingly participate. A contractor offering it is telling you they're willing to commit insurance fraud on your behalf, which should end the conversation.
Read what you sign. Storm-chasing outfits frequently lead with an inspection agreement that is actually a contingency contract assigning them the work if the claim is approved, sometimes with an assignment of benefits that hands them control of your claim, and a cancellation penalty. If a document is presented as a formality, that's exactly when to read it.
Slow down. There is no legitimate reason you need to sign a roofing contract within 48 hours of a hailstorm. Get your claim opened, get an independent inspection, and choose a contractor who will still be in business in five years when a warranty question comes up.
We've been repairing and replacing roofs in North Texas since 1985 and we're here year-round, not just after storms. Free inspections, straight answers about whether it's a repair or a replacement, and we'll work the claim with you. Call 972-921-9488.
Free Estimate, Same-Day Service
We'll beat any written quote in the metroplex. Financing available — call and ask about our finance options.